Wills vs Trusts in New York: 7 Proven Facts on Which One Actually Protects Your Family
Wills vs Trusts in New York: compare probate, estate tax, Medicaid and real costs so you can choose the plan that truly protects your family in 2026.
Wills vs trusts in New York is one of those questions that sounds simple until you start asking around. One friend swears a will is all anyone needs. Another tells you a living trust is the only way to keep your kids out of court. A cousin says trusts are just for rich people. They are all a little bit right, and that is exactly the problem.
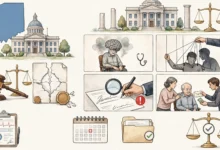
The truth is that New York has its own rules that change the math. Probate here runs through the Surrogate’s Court, and it can take months or even years when things get complicated. New York also has its own estate tax, with a much lower exemption than the federal one and a harsh “cliff” that can cost a family hundreds of thousands of dollars. On top of that, many New Yorkers worry about paying for long-term care, which brings Medicaid rules into the picture.
So the right answer depends on what you own, who you want to protect, and what could go wrong. A young couple renting in Queens has very different needs from a retired teacher with a paid-off house in Westchester and a son with special needs.
In this guide, we will walk through how wills and trusts in New York really work, where each one shines, where each one falls short, and how to figure out which mix fits your family. No legal jargon for its own sake, just the stuff you actually need to decide.
What Is a Will in New York and What Does It Actually Do?
A will is a written set of instructions that tells the world who gets your property after you die and who is in charge of handing it out. That person is your executor. A will only takes effect at death, and it only controls assets that are in your name alone without a named beneficiary.
That last part trips up a lot of people. Your will does not control your 401(k), your life insurance, a bank account with a payable-on-death designation, or a house you own jointly with your spouse. Those pass outside the will, straight to the named person. So when people compare wills vs trusts in New York, they sometimes overestimate how much a will actually covers.
The legal requirements for a valid New York will
New York is fairly strict about how a will is signed. Under the Estates, Powers and Trusts Law, a valid will generally needs:
- To be in writing (New York does not recognize handwritten, unwitnessed wills for most people, with a narrow exception for members of the armed forces during conflict).
- Your signature at the end of the document.
- At least two witnesses who watch you sign or hear you acknowledge your signature, and who sign within 30 days of each other.
- A statement to the witnesses that the document is your will (this is called “publication”).
Most attorneys also add a self-proving affidavit, which the witnesses sign in front of a notary. It saves your family from tracking down witnesses years later when the will goes to court.
What a will does well
- Names a guardian for minor children. This is the big one. A trust cannot do this. If you have kids under 18, you need a will no matter what else you set up.
- Costs less up front. A basic will is usually cheaper and faster to prepare than a full trust plan.
- Is easy to change. You can update a will with a codicil or a new will whenever life changes.
- Offers court oversight. For some families, having a judge watch over the process is actually a feature, not a bug, especially if relatives do not trust each other.
Where a will falls short
- It must go through probate. Every asset the will controls has to pass through the Surrogate’s Court before anyone can touch it.
- It becomes public. Once filed, your will is a public record. Anyone can look up what you owned and who got it.
- It does nothing while you are alive. If you become incapacitated, a will is useless. Your family may need a power of attorney or, worse, a court guardianship proceeding.
- It offers little control after death. A simple will hands assets over outright. If your 19-year-old inherits $300,000 in one lump sum, that is their money to spend however they like.
What happens if you die without a will in New York
If you die without a will, New York’s intestacy law decides who inherits. A spouse with children typically gets the first $50,000 plus half of the rest, and the children split the remainder. Unmarried partners and stepchildren get nothing. Close friends get nothing. For many modern families, that default plan looks nothing like what they would have chosen.
What Is a Trust in New York and How Is It Different?
A trust is a legal arrangement where one person (the trustee) holds and manages property for the benefit of others (the beneficiaries). The person who creates it is called the grantor or settlor. Unlike a will, a trust can work while you are alive, if you become incapacitated, and after you die.
The key thing to understand in any wills vs trusts in New York comparison is that trusts only control what you actually put into them. A trust with nothing in it is just an expensive stack of paper. Moving assets into the trust is called funding, and it is the step people most often skip.
Revocable living trust in New York
A revocable living trust New York residents set up is the most common alternative to a will. You usually act as your own trustee while you are alive, so day-to-day life does not change. You can buy, sell, and spend as normal, and you can change or cancel the trust whenever you want.
When you die or become unable to manage your affairs, a successor trustee you picked steps in and takes over without going to court. That is the main selling point: assets in a properly funded revocable trust avoid probate in New York entirely.
What a revocable trust does not do is shield your assets from creditors, lawsuits, Medicaid, or estate taxes. Because you can take everything back at any time, the law treats those assets as still yours.
Irrevocable trusts in New York
An irrevocable trust is a different animal. Once you transfer assets in, you generally give up control and cannot simply take them back. In exchange, those assets may be protected in ways a revocable trust cannot offer. Common types include:
- Medicaid Asset Protection Trust (MAPT): Used by many New York seniors to protect a home or savings from nursing home costs, subject to the Medicaid look-back period.
- Credit shelter or bypass trust: Used by married couples to make full use of each spouse’s New York estate tax exemption.
- Irrevocable life insurance trust (ILIT): Keeps life insurance proceeds out of your taxable estate.
- Supplemental needs trust: Provides for a disabled loved one without knocking them off government benefits.
Testamentary trusts: a trust inside your will
There is also a middle option many people do not know about. A testamentary trust is written into your will and only comes to life after you die. It lets you hold money for young kids or a spendthrift adult child, but since it is created by the will, it still goes through probate first. It is a useful tool when control matters more than speed.
The New York Probate Process: Why It Matters in the Wills vs Trusts in New York Debate
Probate is the biggest practical difference between a will and a trust. If your main asset passes under a will, your family will be dealing with the New York probate process in the Surrogate’s Court of the county where you lived. New York has one of these courts in each of its 62 counties.
How probate works, step by step
- The executor files a probate petition with the Surrogate’s Court, along with the original will and a certified death certificate.
- Close relatives are notified. Your legal heirs (the people who would inherit if there were no will) must be served with notice or sign a waiver, even if the will leaves them nothing. This gives them a chance to object.
- The court reviews the will and, if everything is in order, issues Letters Testamentary, which give the executor legal authority to act.
- The executor gathers assets, pays debts, files tax returns, and deals with creditors.
- Assets are distributed to the beneficiaries, and the estate is formally closed, either informally with receipts and releases or through a court accounting.
An uncontested probate in a smooth county might take several months to get letters issued. Settling the whole estate commonly takes a year or more. If a relative contests the will, or if an heir is hard to locate, it can drag on far longer.
The real costs of probate in New York
Probate is not cheap. Families typically face:
- Court filing fees that scale with the size of the estate.
- Attorney fees, which are often the largest cost.
- Executor commissions set by statute as a percentage of the estate, unless the executor waives them.
- Time costs, like a house sitting empty and unsellable while taxes, insurance, and maintenance keep coming due.
The small estate shortcut
Not every estate needs full probate. If the person who died left personal property of $50,000 or less, the family may be able to use a simpler process called voluntary administration. The New York State Courts guide to small estates explains that this option is available whether or not there was a will. Keep in mind that this limit only counts assets that would otherwise go through probate, so a house or retirement accounts with beneficiaries are treated differently.
Why privacy matters too
A probated will becomes a public court record. For some families that does not matter. For others, especially business owners, people with blended families, or anyone who would rather not advertise who inherited what, it is a real concern. A trust is a private document that generally never gets filed with the court.
Wills vs Trusts in New York: A Side-by-Side Comparison
Here is how the two stack up on the issues New York families ask about most. This is the quickest way to see the will vs trust New York trade-offs in one place.
| Feature | Will | Revocable living trust |
|---|---|---|
| Goes through probate | Yes | No, if properly funded |
| Public record | Yes, once filed | No, stays private |
| Names a guardian for minors | Yes | No |
| Works if you become incapacitated | No | Yes, successor trustee steps in |
| Upfront cost | Lower | Higher |
| Ongoing upkeep | Minimal | Must retitle new assets into trust |
| Easier to contest | Yes, heirs get formal notice | Harder, no automatic court notice |
| Controls out-of-state real estate | Requires extra probate in that state | Avoids it if property is in the trust |
| Protects from NY estate tax | Only with tax planning built in | Only with tax planning built in |
| Protects from Medicaid | No | No (an irrevocable trust is needed) |
The takeaway from the comparison
Notice the last two rows. A lot of people buy a revocable trust believing it saves taxes or protects against nursing home costs. It does neither on its own. The real advantages of a revocable trust are probate avoidance, privacy, incapacity planning, and smoother handling of property in more than one state.
And notice the guardian row. That is why nearly every trust-based plan still includes a short pour-over will. It names guardians and sweeps any assets you forgot to put in the trust into it at death. Those forgotten assets still go through probate, but at least they end up in the right place.
New York Estate Tax: The Cliff Most Families Never See Coming
This is where New York gets tricky, and where the wills vs trusts in New York question can turn into a six-figure issue. New York has its own estate tax, separate from the federal one, and the numbers are very different.
The 2026 numbers
- Federal exemption: $15,000,000 per person in 2026, after the One Big Beautiful Bill Act made the higher exemption permanent.
- New York basic exclusion amount: $7,350,000 for deaths in 2026, up from $7,160,000 in 2025, according to the New York State Department of Taxation and Finance.
- The cliff: If a New York taxable estate goes above 105% of the exclusion, which is $7,717,500 in 2026, the exemption disappears completely. The entire estate becomes taxable from the first dollar, at rates up to 16%.
That means an estate of $7.3 million owes nothing to New York, while an estate of $7.8 million can owe several hundred thousand dollars. That is not a typo. Small differences in value can cause huge differences in tax.
No portability for married couples
At the federal level, a surviving spouse can generally pick up any unused exemption from the first spouse to die. This is called portability. New York does not allow it. The New York exemption is use it or lose it.
Here is why that matters. Say a married couple owns $12 million together, and each spouse’s simple will leaves everything to the other. When the first spouse dies, no tax is due because of the unlimited marital deduction. But the first spouse’s New York exemption is wasted. When the second spouse dies with the full $12 million, the estate is well past the cliff and owes New York tax on all of it.
How trusts help with New York estate tax
This is one area where a trust-based plan can save real money. A credit shelter trust, sometimes called a bypass trust, holds up to the first spouse’s New York exemption amount for the surviving spouse’s benefit, without that money counting toward the survivor’s estate later. Done right, a married couple can shelter roughly double the New York exemption.
To be fair to wills, a credit shelter trust can be built into a will as a testamentary trust. The tax savings are the same. What you give up is probate avoidance. So the honest answer is that tax planning depends on what is written into the documents, not just on whether you pick a will or a trust.
Who should pay attention
If your total estate is anywhere near $7 million, count everything: your home, retirement accounts, life insurance death benefits, brokerage accounts, and business interests. Life insurance alone pushes many middle-class New York families much closer to the line than they think.
Medicaid and Long-Term Care: The Protection Most Families Actually Need
For many New Yorkers, the biggest threat to an inheritance is not estate tax. It is the cost of long-term care. Nursing homes in New York routinely run well over $150,000 a year, and around-the-clock home care can cost about as much. A few years of care can wipe out a lifetime of savings, including the family home.
Why neither a will nor a revocable trust helps here
This is an important point in the wills vs trusts in New York conversation, and it gets glossed over a lot. A will does nothing for Medicaid planning because it only kicks in after death. A revocable living trust does not help either, because Medicaid counts anything you can take back as your own money.
The Medicaid Asset Protection Trust
The tool most New York elder law attorneys use is the Medicaid Asset Protection Trust, an irrevocable trust designed so that the assets inside are no longer counted for Medicaid eligibility. Here is how it typically works:
- You transfer assets such as your house or investments into the trust.
- A trusted person, often an adult child, serves as trustee.
- You can usually keep living in the house and receive income generated by the trust, but you cannot take the principal back.
- After the look-back period has passed, those assets are generally protected if you later need nursing home Medicaid.
For nursing home care, New York uses a five-year look-back. Any transfer into the trust within five years before applying can trigger a penalty period. New York also passed a look-back for home care Medicaid, but its start date has been pushed back more than once, so check the current status with an elder law attorney before relying on it either way.
Bonus benefits of a MAPT
A properly drafted Medicaid trust can also preserve tax advantages. Assets can be set up to get a step-up in cost basis at death, which may save your children a big capital gains bill when they sell the house. And because the trust owns the assets, they avoid probate too.
The catch is timing. The best time to set up a Medicaid trust is while you are healthy, years before you might need care. Waiting until a crisis limits your options.
Which One Protects Your Family Best? Real-Life Scenarios
The answer to wills vs trusts in New York really comes down to your family’s situation. Here are the scenarios that come up most often and what usually makes sense for each.
Young parents with minor children
You need a will, period, because only a will can name a guardian for minor children. But a will alone means any money left to your kids goes into a court-supervised guardianship until they turn 18, and then it is theirs, all at once.
Most estate planners suggest pairing the will with a trust, either a testamentary trust inside the will or a revocable trust. Either one lets you say something like: “use the money for school and health costs, give a third at 25, a third at 30, and the rest at 35.” Also name the trust as beneficiary of your life insurance so the payout lands in the right hands.
Blended families and second marriages
This is where trusts really earn their keep. Picture a man with two kids from his first marriage who remarries. If his will leaves everything to his new wife, she can legally change her own will and leave it all to her kids instead. His children may end up with nothing.
A trust can provide income and housing for the surviving spouse for life, then pass what is left to the children from the first marriage. Everyone is protected, and the plan cannot be quietly rewritten later. Keep in mind that New York gives a surviving spouse a right of election, generally the greater of $50,000 or one-third of the estate, so any plan has to account for that.
A child or relative with special needs
Leaving money outright to someone who receives SSI or Medicaid can disqualify them from those benefits. A supplemental needs trust (often called a special needs trust) solves this. The trustee can pay for things that improve quality of life, like therapy, travel, or education, without counting as the beneficiary’s own assets. A will alone simply cannot do this safely.
Owners of real estate in more than one state
If you own a condo in Florida or a cabin in Vermont, a will-only plan means your family may have to go through a second probate, called ancillary probate, in that state. Putting out-of-state property in a revocable trust avoids that headache.
Single people and couples with modest, simple estates
If you rent, have mostly retirement accounts with beneficiaries named, and your bank accounts have payable-on-death designations, you might pass almost everything outside probate already. A well-drafted will, updated beneficiary forms, a power of attorney, and a health care proxy may be all you need for now.
Cost of a Will vs a Trust in New York
Prices vary a lot by county, attorney, and how complex your situation is. As a rough guide, a simple will package from a New York attorney often runs from several hundred dollars to a couple thousand. A revocable trust plan, including the pour-over will, power of attorney, and health care proxy, usually costs several thousand dollars. Medicaid trusts and tax-driven plans typically cost more.
The smarter way to compare the cost of wills vs trusts in New York is total cost over time. A will is cheaper now, but your family pays for probate later. A trust costs more now, but can save probate fees, court costs, and months of delay. For a family with a house and a few hundred thousand in savings, the trust often comes out ahead. For a renter with modest savings, the will usually wins.
Common Myths About Wills and Trusts in New York
Let’s clear up a few things people believe about wills vs trusts in New York that are not quite true.
- “Trusts are only for the wealthy.” Not true. Plenty of middle-class New Yorkers use trusts to avoid probate on a single home or to protect a child with special needs.
- “A living trust avoids estate taxes.” A revocable trust does not reduce taxes on its own. Only specific tax planning inside the documents does that.
- “If I have a will, my family avoids court.” The opposite is true. A will is your ticket into Surrogate’s Court.
- “My spouse gets everything automatically.” Not under New York intestacy rules if you have children. And jointly owned property only helps until the second spouse dies.
- “Once I sign a trust, I’m done.” A trust only controls assets you actually move into it. An unfunded trust protects nothing.
The Biggest Estate Planning Mistakes New York Families Make
Even a well-drafted plan can fail if the details slip. These are the mistakes that cause the most trouble:
- Never funding the trust. Signing the trust but never retitling the house deed or bank accounts sends everything right back to probate.
- Outdated beneficiary designations. An ex-spouse still listed on a life insurance policy or 401(k) can end up with the money, regardless of what your will says.
- Ignoring incapacity. Without a durable power of attorney and a health care proxy, your family may need a court guardianship just to pay your bills.
- Forgetting the estate tax cliff. Couples near the New York exclusion amount who use simple “everything to my spouse” wills can lose a full exemption.
- Waiting too long for Medicaid planning. The five-year look-back means the clock needs to start well before care is needed.
- DIY documents that miss New York’s signing rules. An improperly witnessed will can be thrown out, leaving your family under intestacy law.
- Never updating the plan. Marriages, divorces, births, deaths, moves, and new property all call for a review. A good rule is to look at your plan every three to five years.
How to Choose Between a Will and a Trust in New York
If you are still on the fence about wills vs trusts in New York, walk through these questions. Your answers will usually point you in the right direction.
- Do you have children under 18? Then you need a will to name a guardian, and probably a trust to manage their money.
- Do you own a home or other real estate? Real estate is the asset most likely to get stuck in probate. A revocable trust is often worth it here.
- Is your estate worth more than about $5 million, or near the New York exclusion amount? Then you need tax planning, often with a credit shelter trust.
- Are you over 60 or worried about long-term care costs? Talk to an elder law attorney about a Medicaid Asset Protection Trust.
- Is your family blended, or is there a beneficiary with special needs or money troubles? A trust gives you control that a simple will cannot.
- Do you value privacy? A trust keeps your affairs out of the public record.
- Is your estate small and simple, with beneficiaries already named on most accounts? A will plus updated beneficiary forms may be enough for now.
For most New York families, the honest answer is not one or the other. It is a combination: a trust to hold the main assets, a pour-over will as a safety net, plus a power of attorney and health care proxy. The best New York estate planning strategy is the one that fits what you own and who you are trying to protect.
Frequently Asked Questions About Wills vs Trusts in New York
Is a trust better than a will in New York?
Not always. A trust is usually better if you own a home, want privacy, have property in another state, or need to plan for incapacity. A will is often enough for people with simple estates. Most families end up with both.
Can I write my own will in New York?
You can, but it has to meet New York’s signing and witnessing rules exactly. Small mistakes can invalidate the whole thing, so having an attorney supervise the signing is worth considering.
Does a revocable trust protect my house from a nursing home?
No. Because you can revoke it, Medicaid treats the house as yours. You would need an irrevocable Medicaid Asset Protection Trust, set up at least five years before applying for nursing home Medicaid.
How long does probate take in New York?
A simple, uncontested probate often takes several months just to get Letters Testamentary, and a year or more to fully settle the estate. Contested cases can take years.
What should I weigh first in the wills vs trusts in New York decision?
Start with three questions: do you have minor children, do you own real estate, and is your estate close to the New York exclusion amount? Those answers decide most of the wills vs trusts in New York debate for typical families.
Do I still need a will if I have a trust?
Yes. A pour-over will catches anything left outside the trust and is the only place you can name a guardian for minor children.
Conclusion
When it comes to wills vs trusts in New York, there is no one-size-fits-all winner, but there is a right answer for your family. A will is essential for naming guardians and works well for simple estates, yet it sends your assets through Surrogate’s Court, becomes public, and does nothing if you become incapacitated. A revocable living trust avoids probate, keeps things private, and lets a trusted person step in during illness, but it only works if you fund it and it does not, by itself, cut taxes or protect against nursing home costs. For New Yorkers, the state’s $7,350,000 estate tax exclusion, the brutal cliff just above it, the lack of portability between spouses, and the five-year Medicaid look-back are the factors that turn this from a paperwork choice into real financial protection, which is why most families do best with a combined plan built by a New York estate planning attorney and reviewed every few years as life changes.